Monthly Cost Ranges
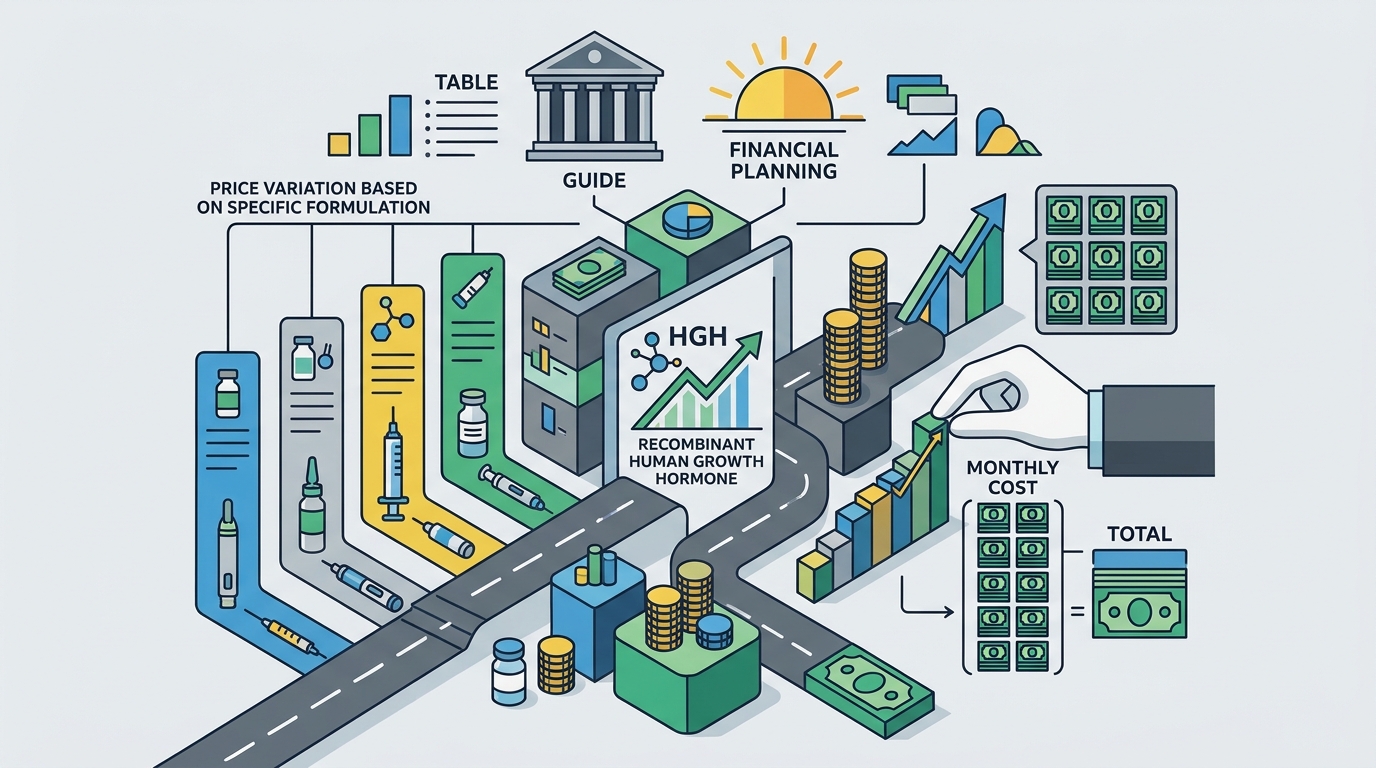
Understanding the baseline cost of growth hormone therapy is the first step in financial planning. The price varies significantly based on the specific formulation prescribed. Recombinant human growth hormone (HGH) is the standard treatment for eligible children with growth hormone deficiency or other recognized indications. The cost is not a flat rate; it scales with the child's body weight and the specific brand or generic alternative used.
Brand vs. Generic Options
Brand-name growth hormone products often carry higher price tags compared to generic alternatives, though availability varies by region and insurance formulary. In the United States, the list price for brand-name HGH can be substantial. However, the actual out-of-pocket cost is often lower due to insurance negotiations and manufacturer discounts. Families should always verify the specific product covered by their plan, as formulary status changes frequently.
Factors Influencing Monthly Price
Several variables affect the final monthly bill. The child's weight is the primary driver, as dosing is calculated per kilogram. The stage of puberty also matters, as dosing requirements may shift during this period. Additionally, the frequency of administration, whether daily or long-acting, impacts the total cost. Long-acting formulations may have a higher per-dose cost but reduce the burden of daily injections.
| Child Weight | Estimated Monthly Cost (Cash Price) | Notes |
|---|
These figures represent cash prices and may differ significantly with insurance. Long-term cost considerations are crucial for families planning for multi-year treatment. Always consult with a provider to get an accurate estimate based on your specific insurance plan. according to Home Short History
Insurance Coverage Impact
Insurance coverage is the single most significant factor in determining out-of-pocket costs. Most major insurance plans cover growth hormone therapy for medically indicated conditions, such as growth hormone deficiency (GHD). However, coverage is not automatic. It requires a documented diagnosis and prior authorization from the insurance company.
Eligibility and Diagnosis
Insurers typically require a confirmed diagnosis before approving coverage. Growth Hormone Deficiency (GHD) is a specific medical condition where the pituitary gland produces insufficient growth hormone. Other conditions, such as Turner Syndrome or Prader-Willi Syndrome, may also be covered. Idiopathic Short Stature (ISS) coverage varies widely by plan. Some insurers cover ISS, while others do not. Families should review their policy details carefully.
Prior Authorization Process
The prior authorization process involves submitting medical records, growth charts, and test results to the insurer. This process can take several weeks. During this time, the provider must demonstrate that the treatment is medically necessary. If denied, families can appeal the decision. Understanding the specific criteria your insurer uses is essential. Cash-pay options may be considered if insurance is denied or if the family prefers to avoid the administrative burden.
Weight Based Dosing
Growth hormone dosing is strictly weight-based. The standard dose for GHD is typically calculated in micrograms per kilogram of body weight per day. This means that as a child grows, their dose increases, and so does the cost. This dynamic pricing model is a key consideration for long-term financial planning.
Calculating the Dose
For example, a child weighing 30 kg might receive a dose of 0.2 mg/kg/day. This results in a total daily dose of 6 mg. The monthly cost is derived from this total. As the child gains weight, the dose is adjusted upward. This incremental increase can lead to a gradual rise in monthly costs over the course of treatment. Families should anticipate this trajectory when budgeting.
Impact of Puberty
Puberty can influence dosing requirements. During this period, growth velocity may change, and the provider may adjust the dose to optimize growth potential. The timing of puberty onset is a critical factor in treatment planning. HGH therapy for height is most effective when started before growth plates close. Monitoring growth velocity and bone age helps determine the appropriate dose adjustments.
Manufacturer Assistance Programs
For families without insurance or those facing high out-of-pocket costs, manufacturer assistance programs can provide significant relief. Most major growth hormone manufacturers offer patient assistance programs (PAPs) for eligible individuals. These programs may provide the medication at a reduced cost or for free, depending on the family's financial situation.
Eligibility Criteria
Eligibility for PAPs is usually based on income and insurance status. Families with low to moderate incomes and no insurance coverage are often the primary beneficiaries. The application process requires documentation of income and insurance status. Approval times vary, so it is best to apply early in the treatment process. Frequently asked questions about HGH often address these financial support options.
Co-Pay Cards and Discounts
Even for insured families, co-pay cards and discounts can reduce out-of-pocket expenses. These cards are typically provided by the manufacturer and can be used at the pharmacy. They may cover a portion of the monthly cost, subject to plan limits. Families should check with their provider to see which assistance programs are available for their specific medication.
Key Takeaways
- Insurance coverage is the primary determinant of out-of-pocket costs, requiring prior authorization for most plans.
- Dosing is weight-based, meaning costs increase as the child grows.
- Manufacturer assistance programs can significantly reduce costs for uninsured or underinsured families.
- Idiopathic Short Stature coverage varies by insurance plan and requires careful review of policy details.
- Long-acting formulations may have higher per-dose costs but offer convenience.
- Consulting with a pediatric growth specialist helps navigate insurance and financial planning.
Frequently Asked Questions
How much does growth hormone therapy cost per month for a child?
Does insurance cover growth hormone for short stature?
Coverage depends on the diagnosis. GHD is widely covered. Idiopathic Short Stature coverage varies by plan. Prior authorization is required.
How is the dose calculated?
Dosing is based on body weight in kilograms. The dose increases as the child grows, affecting monthly costs.
Are there financial assistance programs?
Yes, most manufacturers offer patient assistance programs for eligible families. These can reduce or eliminate costs for uninsured patients.
What is the difference between brand and generic HGH?
Brand-name products may cost more. Generic alternatives are often less expensive but availability varies. Insurance formulary status determines which is covered.
How long does treatment usually last?
Treatment continues until growth plates close or the child reaches their adult height potential. This can span several years.
Can I pay cash if insurance denies coverage?
Yes, cash-pay options are available. Manufacturer discounts and assistance programs can help reduce the cash price.
Conclusion
Navigating the cost of growth hormone therapy requires a clear understanding of dosing, insurance, and assistance options. At HGH for Children, we help families understand these financial factors as part of a comprehensive growth evaluation. Our team guides you through insurance verification and assistance program applications to ensure you have the best possible plan. To discuss your child's growth and financial options, today.