Insurance companies evaluate pediatric growth hormone (HGH) requests against strict clinical criteria before granting authorization. These requirements focus on documented growth deficits, specific medical diagnoses, and the completion of standardized diagnostic testing. Understanding these checkpoints helps families prepare the necessary documentation for a smoother approval process.
1. Documented Short Stature Below the 2.3rd Percentile
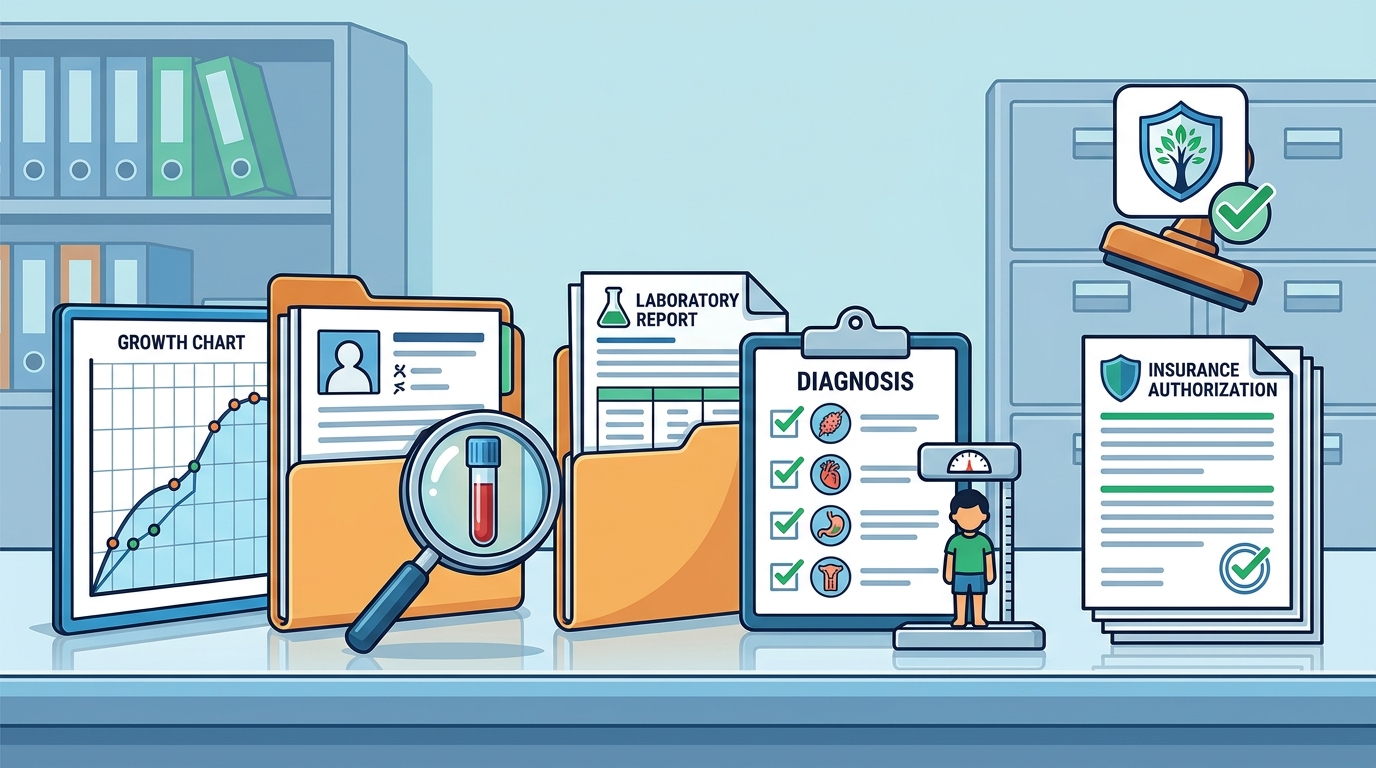
Insurers require objective proof that a child's height falls significantly below the average for their age and sex. Most insurance plans mandate that a child's height be below the 2.3rd percentile on standardized growth charts. This threshold ensures that treatment is reserved for children with clinically significant short stature rather than those who are simply on the shorter end of the normal range. Clinicians must provide recent height measurements taken by a qualified healthcare provider to satisfy this requirement.
2. Confirmed Growth Hormone Deficiency Diagnosis
Many plans require a specific diagnosis of Growth Hormone Deficiency (GHD) rather than general short stature. Growth Hormone Deficiency is a condition where the pituitary gland does not produce enough growth hormone to support normal development. Insurance providers often distinguish between GHD and other causes of short stature, such as constitutional growth delay or idiopathic short stature. A definitive diagnosis usually requires specific provocative testing to confirm that the pituitary gland is not responding appropriately to stimulation.
3. Low IGF-1 and IGFBP-3 Laboratory Results
Baseline blood work showing low levels of Insulin-Like Growth Factor-1 (IGF-1) and Insulin-Like Growth Factor Binding Protein-3 (IGFBP-3) is a standard prerequisite. IGF-1 is a protein that reflects the body's response to growth hormone and is essential for bone growth. Insurers typically require these levels to be below the age and sex-specific reference ranges. These laboratory values help confirm that the growth hormone axis is not functioning optimally and support the clinical picture of a growth disorder.
4. Delayed Bone Age Assessment
A bone age X-ray demonstrating skeletal immaturity is frequently required to establish remaining growth potential. Bone age is a measure of skeletal maturity determined by an X-ray of the left hand and wrist. Insurers look for a bone age that is delayed compared to the child's chronological age, which suggests that the growth plates are still open and the child has time to grow. This assessment helps determine whether treatment is likely to be effective before the growth plates close.
5. Comprehensive Medical History and Physical Examination
Providers must document a thorough review of the child's medical history, family history, and physical development. This includes evaluating for other conditions that might affect growth, such as thyroid disorders, celiac disease, or chronic illnesses. Insurers require evidence that these alternative causes have been ruled out or are being managed. A detailed physical examination report, including pubertal staging, is often part of the required documentation to ensure the diagnosis is accurate.
6. Growth Velocity Below Expected Rates
Insurers often require evidence that the child's growth velocity is slower than expected for their age and pubertal stage. Growth velocity is the rate at which a child grows in height over a specific period, usually measured in inches per year. Before puberty, a growth rate below approximately 2 inches per year may warrant further evaluation. Documenting a declining growth curve or a failure to maintain a consistent percentile over time strengthens the case for treatment approval.
7. Prior Authorization and Step Therapy Compliance
Administrative requirements, such as prior authorization and step therapy, must be completed before treatment begins. Prior authorization is a process where the insurance company reviews the medical necessity of the treatment before approving coverage. Some plans may require step therapy, which means trying other treatments or completing additional evaluations before HGH is approved. Families should work with their insurance provider to understand these administrative steps and ensure all required forms are submitted correctly.
Choosing the Right Path for Your Child
When navigating these insurance requirements, focus on building a complete and accurate medical record. Ensure that all diagnostic tests are up to date and that the clinical diagnosis is clearly documented. If your child does not meet the strict criteria for insurance coverage, discuss alternative options or cash-pay programs with your healthcare provider. At HGH for Children, we help families understand their child's growth patterns and guide them through the evaluation process with clarity and care.
Frequently Asked Questions
Does insurance cover growth hormone therapy for all short children?
No, insurance typically covers growth hormone therapy only for children with a confirmed medical diagnosis, such as Growth Hormone Deficiency or specific conditions like Turner syndrome. Children with constitutional growth delay or idiopathic short stature may not qualify for insurance coverage depending on the plan's specific criteria.
What is the most common reason for insurance denial?
The most common reason for denial is a lack of documented Growth Hormone Deficiency. If a child is short but does not have a confirmed hormonal deficiency, insurers may deny the claim. Ensuring that all provocative testing and laboratory results are included in the prior authorization request is critical.
How long does the insurance approval process take?
The approval process can take anywhere from a few days to several weeks, depending on the insurance company and the complexity of the case. Providing complete and accurate documentation upfront can help expedite the review process and reduce the likelihood of delays.
Can I appeal an insurance denial?
Yes, families have the right to appeal an insurance denial. An appeal involves submitting additional medical evidence or a letter of medical necessity from the treating physician. It is important to review the denial letter carefully to understand the specific reason for the rejection and address it in the appeal.
What is the role of bone age in insurance approval?
Bone age helps determine if a child has remaining growth potential. Insurers require a bone age X-ray to ensure that the growth plates are still open. If the bone age is significantly advanced, indicating that the child is close to skeletal maturity, insurers may deny treatment because the potential for height gain is limited.