Understanding the Core Monthly Medication Cost
Insurance coverage plays a pivotal role in determining your out-of-pocket expense. Many commercial health plans cover HGH for approved indications, such as growth hormone deficiency (GHD) or idiopathic short stature (ISS). However, coverage limits vary widely. Some plans have a cap on the number of units covered per month, while others require a specific prior authorization process. Families without insurance, or those with high deductibles, often face the full cash price. This is why a thorough financial review is a standard part of the consultation process at our clinic.
Insurance Coverage and Prior Authorization
Securing insurance approval is often the most time-consuming aspect of budgeting for HGH. Insurers typically require proof of a specific diagnosis before approving coverage. For example, if a child is diagnosed with GHD, the insurer may require stimulation test results. If the diagnosis is ISS, they may require documentation of height below a specific percentile, such as the 2.5th percentile. Without this documentation, the claim may be denied, leaving the family responsible for the full cost.
Additional Costs: Labs, Monitoring, and Supplies
Cash-Pay Options and Financial Planning
For families who do not have insurance coverage for HGH, cash-pay options provide an alternative. The cash price for growth hormone is generally lower than the wholesale price charged to insurance companies, but it is still a significant monthly expense. Some clinics offer cash-pay programs that include the medication and monitoring visits in a bundled package. This can simplify budgeting by providing a single, predictable monthly fee. However, it is crucial to verify what is included in the package. Does it cover all necessary labs? Does it include follow-up appointments? Clarifying these details upfront helps families plan their finances accurately.
Key Takeaways
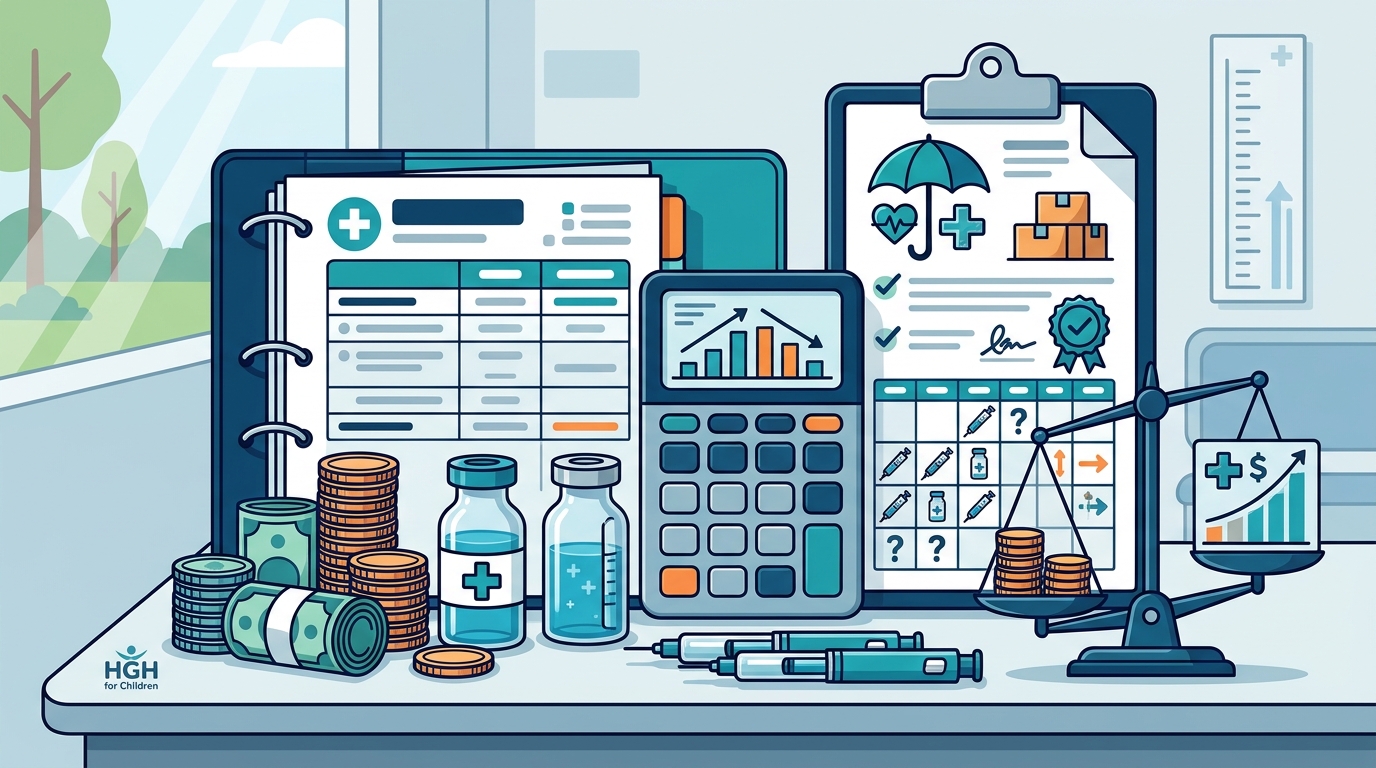
- Insurance coverage significantly reduces out-of-pocket costs, but prior authorization is often required.
- Cash-pay options are available for uninsured families, often at a lower per-unit price than insurance rates.
- Total treatment cost depends on the duration of therapy, which varies based on the child’s age and skeletal maturity.
- Proactive documentation and insurance verification are critical to avoiding claim denials and unexpected expenses.
Frequently Asked Questions
Does insurance cover growth hormone for short stature?
Insurance coverage for growth hormone depends on the specific diagnosis. Most plans cover HGH for growth hormone deficiency (GHD). Coverage for idiopathic short stature (ISS) is less consistent and often requires the child to be below a specific height percentile, such as the 2.5th percentile. You should verify your plan’s specific criteria with your insurance provider before starting treatment.
How much does HGH cost without insurance?
Are there additional costs besides the medication?
How long does a child usually need growth hormone treatment?
The duration of treatment varies by individual. It typically continues until the child’s growth plates close, which can take several years. The exact timeline depends on the child’s age at the start of treatment, their bone age, and their response to the medication. Regular monitoring helps determine when to continue or stop therapy.
Can I switch brands to save money?
Switching brands may affect cost, but it requires medical approval. Different brands of growth hormone have different dosing requirements and costs. Your healthcare provider can discuss whether a switch is appropriate based on your child’s response to the current medication and your insurance coverage. Always consult your doctor before making any changes to your treatment plan.
Next Steps for Families
Understanding the financial aspects of growth hormone treatment is a crucial part of the decision-making process. By reviewing your insurance benefits, estimating medication costs, and planning for monitoring expenses, you can create a realistic budget. At HGH for Children, we provide personalized guidance to help families navigate these financial and medical considerations. Our team works with you to verify insurance coverage and discuss treatment options that align with your family’s needs and budget.
To begin your evaluation, to schedule a consultation. We will review your child’s growth history and discuss the financial and medical steps involved in treatment.